Fold Fair-Value Estimate Falls as Analyst Targets Diverge
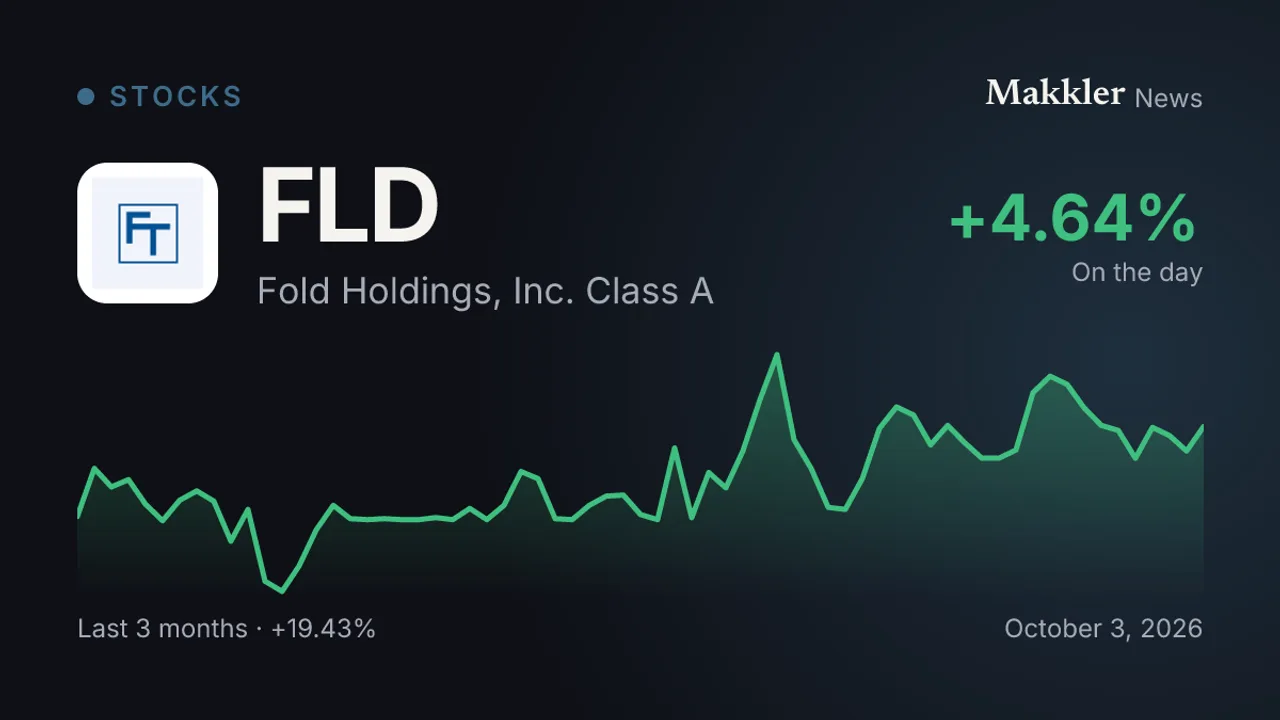
A valuation estimate was lowered, while analysts cited crypto-market pressure and a slower-than-expected rollout of Fold’s Bitcoin rewards card.
Fold Holdings’ fair-value estimate was lowered to US$2.10 from US$2.46, according to a Simply Wall St analysis. Analyst price targets cited in the report range from US$0.70 to US$2.50.
Northland cut its target to US$2.50 from US$3.50 but maintained its Outperform rating. Cantor Fitzgerald lowered its target to US$0.70 from US$1.70, citing a softer crypto trading backdrop and a slower-than-expected rollout of Fold’s Bitcoin Rewards Credit Card.
Jones recently started coverage with a Buy rating and a US$1 target. The wide gap among the three firms’ targets reflects differing views on Fold’s valuation and growth prospects, the report said.
The revised fair-value framework also adjusted its revenue-growth assumption to 34.11% from 33.51%. Its future price-to-earnings estimate fell to 10.58 times from 12.54 times, while its discount rate moved to 8.72% from 8.76%.
The analysis points to the card rollout and crypto-market conditions as factors in the debate over Fold. It also identifies operating losses, cash burn and reliance on a small group of large partners as risks.
This article was produced with the help of AI technology. Based on reporting by the outlets listed above.