Zions’ Six-Month Rally Meets Higher Costs and Credit Risks
Stronger deposits and margins support the bank’s growth outlook, but rising expenses and expected credit losses cloud the picture.
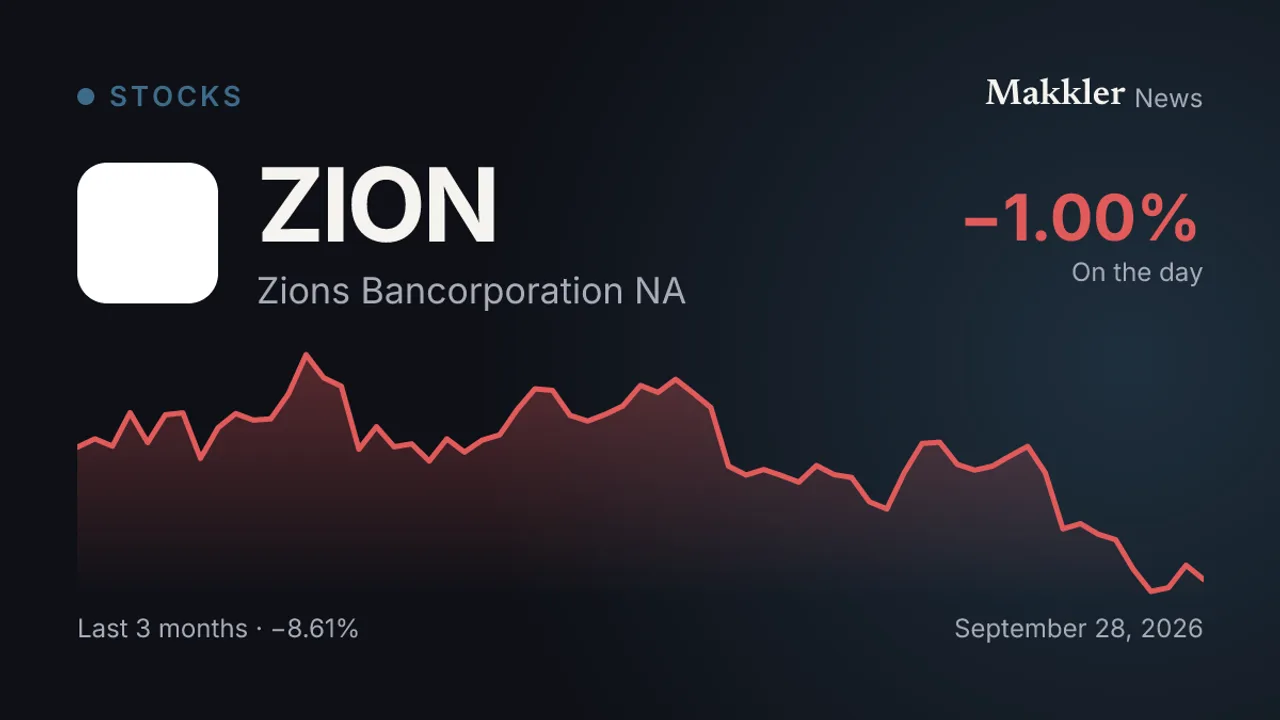
Zions Bancorporation shares gained 14.8% over the past six months, beating the industry and two named peers, but trailing the S&P 500’s 22% rise. Wintrust Financial gained 9.4%, while WaFd rose 0.9%, according to Zacks Equity Research.
As of 14:33 UTC on Sept. 28, Zions traded at $63.40, down 0.67% since the previous close. Zacks said revenue, loans and leases improved in the first half of 2026, and projected net interest income to grow at a 4.3% annual rate through 2028.
The bank’s net interest margin rose to 3.21% in 2025 from 3% in 2024. Customer deposits, excluding brokered deposits, reached $72.7 billion on June 30, 2026, while total borrowed funds fell 53% year over year.
Zacks also pointed to cost and credit risks. It expects non-interest expenses to rise 4.7% in 2026 and provisions for loan losses to grow at a 13.8% annual rate over the next three years. The research firm said Zacks’ consensus estimate for 2026 earnings had fallen 2.3% over the prior 30 days, while the 2027 estimate was revised slightly higher.
This article was produced with the help of AI technology. Based on reporting by the outlets listed above.