Amneal Raises 2026 Revenue and Earnings Targets After Q3 Growth
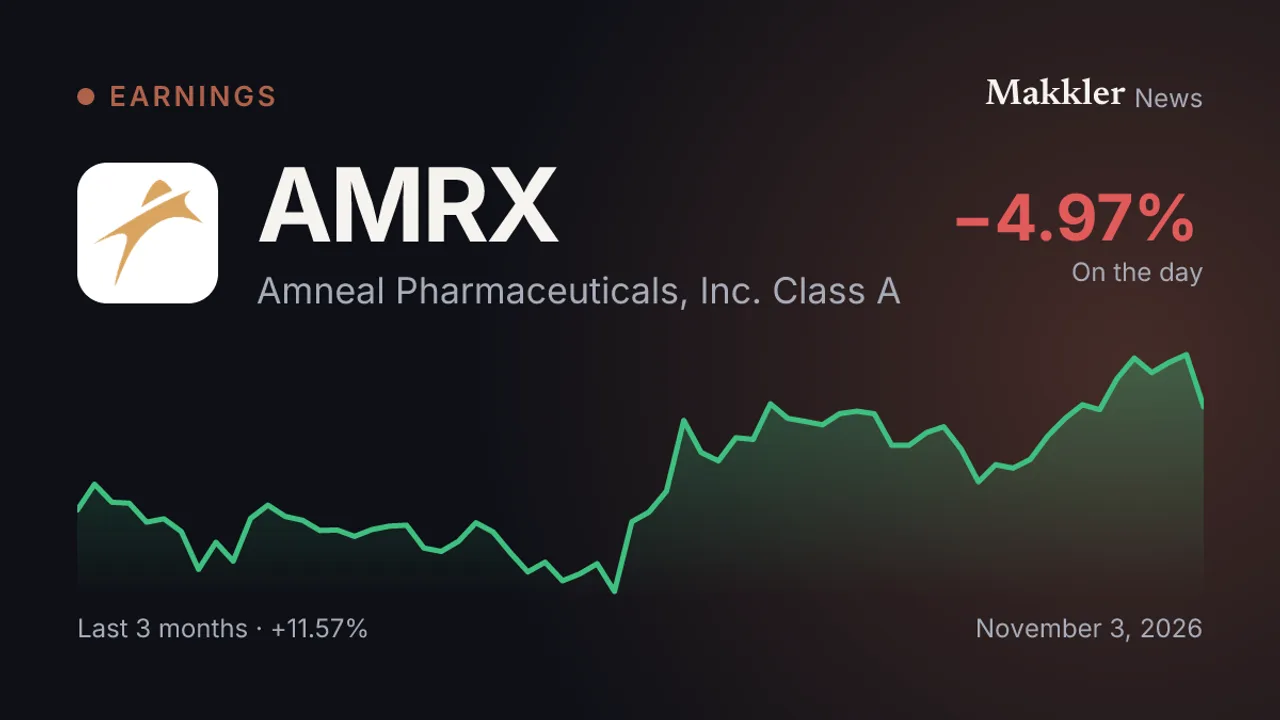
Amneal reported higher third-quarter revenue and adjusted EBITDA, while posting a net loss and increasing several full-year financial targets.
Key takeaways
- Third-quarter revenue rose 10% to $863 million year over year.
- Amneal reported a $22 million net loss attributable to the company.
- The company raised its 2026 revenue, adjusted EBITDA and adjusted EPS guidance.
Amneal Pharmaceuticals reported third-quarter revenue of $863 million, up 10% from a year earlier. Adjusted EBITDA, a non-GAAP measure, increased 30% to $207 million.
Affordable Medicines revenue grew 19%, with the company citing biosimilars, women’s health patches and new launches. Specialty revenue rose 20%, while AvKARE revenue fell 17%, which Amneal attributed to a non-recurring product launch in the prior-year quarter.
Amneal recorded a $22 million net loss attributable to the company, compared with net income of $2 million a year earlier. The company said higher revenue and gross profit were more than offset by non-recurring acquisition and integration costs and a higher tax provision. Diluted loss per share was 6 cents; adjusted diluted EPS was 26 cents, up from 17 cents.
The company raised its 2026 guidance for revenue to $3.15 billion to $3.25 billion, adjusted EBITDA to $800 million to $815 million, and adjusted diluted EPS to $1.04 to $1.08. Its prior ranges were $3.10 billion to $3.20 billion, $750 million to $780 million, and $0.96 to $1.06, respectively.
Amneal lowered its operating cash flow guidance to $325 million to $375 million from $350 million to $400 million. It said the update reflects working capital, including higher inventory in key growth areas.
This article was produced with the help of AI technology. Based on reporting by the outlets listed above.