IBM lifts software growth outlook after quarterly revenue tops estimates
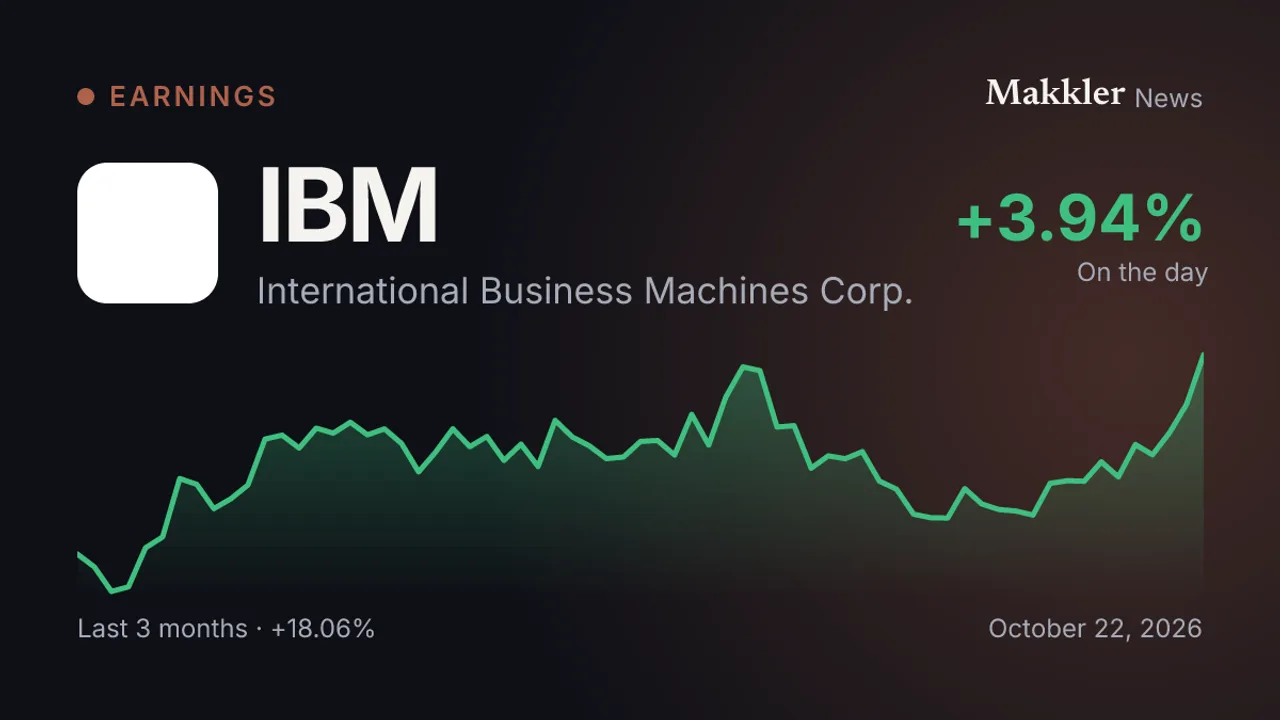
The company raised its software forecast as third-quarter revenue and adjusted earnings exceeded analyst expectations, while its broader revenue outlook held steady.
Key takeaways
- IBM expects annual software revenue growth of 7% to 8%, up from its previous 6% to 8% forecast.
- Third-quarter revenue reached $17.10 billion, and adjusted earnings were $2.95 per share.
- IBM kept its 2026 constant-currency revenue growth outlook at 4% to 5%.
IBM raised its annual software revenue growth forecast after reporting third-quarter revenue of $17.10 billion and adjusted earnings of $2.95 per share, both above analyst estimates. The company now expects software revenue growth of about 7% to 8%, compared with its previous range of 6% to 8%.
Software revenue rose 8.3% to $7.80 billion, according to Reuters. IBM finance chief James Kavanaugh said delayed software deals that had concerned investors were beginning to close. About 25% of transaction-processing revenue came from deals deferred from the second quarter, he said, while the rest was new business.
IBM’s total revenue increased about 5% from a year earlier. Net income rose to $2.19 billion from $1.74 billion, according to the company’s results. Infrastructure revenue gained 4.2% to $3.71 billion, while consulting revenue was flat at $5.34 billion.
The company maintained its 2026 forecast for constant-currency revenue growth of 4% to 5%. IBM also expects full-year free cash flow to increase by more than $1 billion, an improvement on the approximately $1 billion increase it forecast in July.
CEO Arvind Krishna said customers were deploying “Super Intelligence” to transform their operating models. Kavanaugh said AI represented about 30% of consulting revenue and 35% of the unit’s backlog in the quarter.
This article was produced with the help of AI technology. Based on reporting by the outlets listed above.