Micron’s $50 Billion Forecast Fuels Bullish Case Ahead of Earnings
Record memory sales and long-term customer deals strengthen the case for Micron, but investors face a key test on September 30.
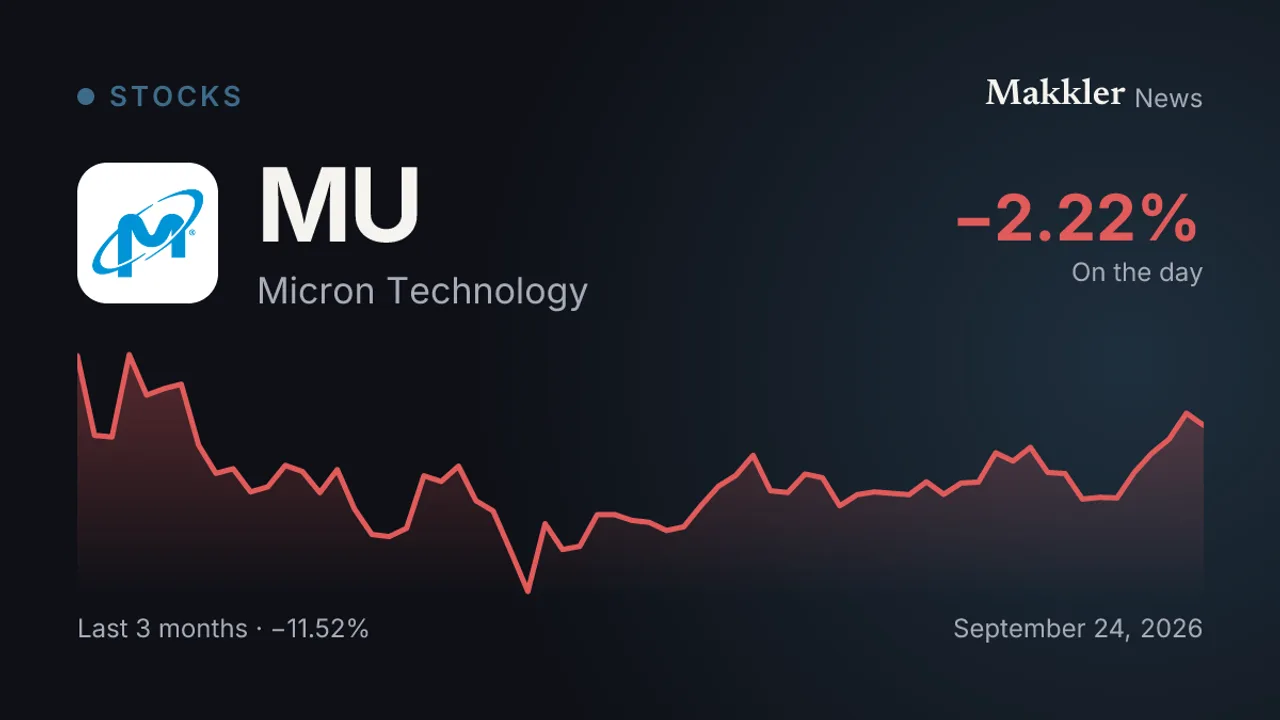
Micron Technology forecast fiscal fourth-quarter revenue of $50 billion, plus or minus $1 billion, as demand for memory chips surges. The company’s September 30 earnings report will show whether sales and margins are keeping pace with that outlook.
The forecast follows a record fiscal third quarter. Micron reported $41.46 billion in revenue for the quarter ended May 28, up from $9.30 billion a year earlier.
Memory pricing drove much of that growth. DRAM revenue rose 343% year over year to $31.3 billion, while NAND revenue climbed 361% to $9.9 billion, according to Micron’s earnings materials. The company also forecast a fourth-quarter gross margin of about 86%.
Micron’s bullish case extends beyond one quarter. It said 16 strategic customer agreements cover about 20% of its DRAM volume and one-third of its NAND volume through 2030. Fourteen agreements represent about $100 billion in minimum revenue over their remaining terms.
Those contracts offer more visibility into future sales, but they do not eliminate the risk of a downturn. Memory has historically been a cyclical business: if supply catches up with demand, chip prices and profits can fall quickly.
Barchart’s buy case also points to a low forward earnings multiple of about 6.4. That figure depends on profit forecasts; a low multiple can be less reassuring if earnings are near a cyclical peak.
The September 30 report is the next test for the investment case. Investors will be watching whether Micron meets its $50 billion sales outlook and whether management sees tight supply and strong pricing continuing into future quarters.
This article was produced with the help of AI technology. Based on reporting by the outlets listed above.