OCBC lifts 2026 outlook after quarterly profit tops estimates
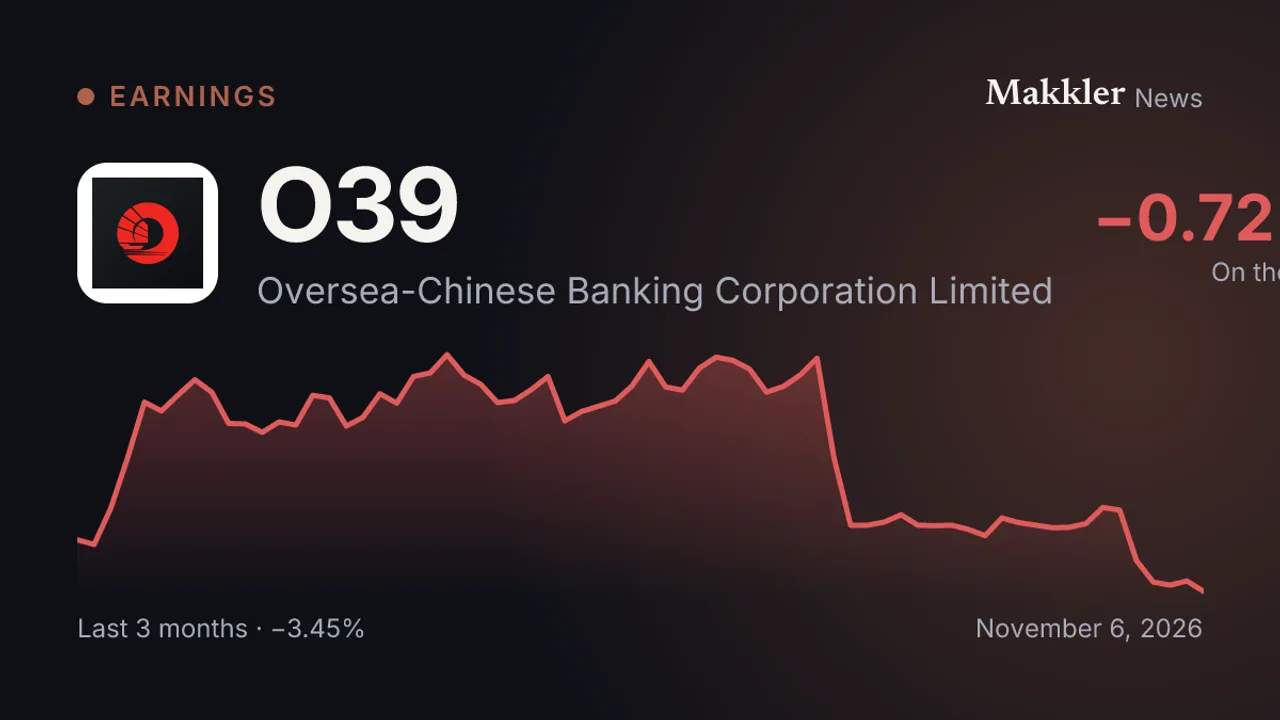
Third-quarter net profit rose 3% to S$2.04 billion, while the bank raised its loan-growth forecast and lowered its credit-cost range.
Key takeaways
- OCBC’s third-quarter net profit rose 3% to S$2.04 billion.
- Net interest income increased 4%, while net interest margin fell 18 basis points year on year.
- The bank raised its 2026 loan-growth forecast to the low double digits.
OCBC raised its 2026 outlook after third-quarter net profit climbed 3% year on year to S$2.04 billion. The result was slightly above the S$2.01 billion average estimate of four analysts cited by LSEG.
Net interest income rose 4% to S$2.31 billion, supported by growth in customer loans and high-quality non-commercial assets. Net interest margin, a measure of lending profitability, fell 18 basis points to 1.66%.
Non-interest income declined 10% to S$1.42 billion, mainly reflecting weaker investment performance at insurance arm Great Eastern. The bank said mark-to-market losses on Great Eastern’s bond portfolio weighed on results, while second-quarter equity gains were not repeated.
OCBC now expects loan growth in the low double digits, compared with its earlier forecast of high-single-digit to low-double-digit growth. It expects total income to grow by at least a mid-single-digit percentage, net interest income to be flat or decline slightly, and credit costs of 15 to 20 basis points.
The bank said it is monitoring the Middle East conflict, energy markets and conditions in Indonesia. OCBC shares were at S$27.77, down 0.57% since the previous close, as of 02:23 UTC on Friday.
This article was produced with the help of AI technology. Based on reporting by the outlets listed above.