Philips Reports 8% Order Growth, Repeats 2026 Outlook
The health technology company posted higher quarterly sales and margins, while recording a €288 million provision tied to Respironics proceedings.
Key takeaways
- Comparable order intake rose 8% in the third quarter.
- Philips recorded a €288 million provision tied to the Respironics investigations.
- The company reiterated its full-year 2026 outlook.
Philips reported an 8% rise in comparable order intake and 3% comparable sales growth in the third quarter. The company also recorded a €288 million provision after reaching an agreement in principle with the US Department of Justice over investigations related to the Respironics recall.
Adjusted EBITA margin increased 70 basis points to 13.0%. Philips said higher sales, improved gross margin and productivity measures supported the increase, partly offset by cost inflation. Operating cash flow was €544 million and free cash flow was €384 million.
The DOJ agreement is subject to finalizing documentation, and payment is expected in the first quarter of 2027, Philips said. The company’s outlook assumes that payment and excludes other ongoing Respironics-related proceedings, including an investigation by US state attorneys general.
Philips reiterated its full-year 2026 outlook, which calls for comparable sales growth of 3% to 4.5%, an adjusted EBITA margin of 13.5% to 14.0%, and free cash flow of €1.5 billion to €1.7 billion. The margin outlook includes an estimated benefit of about 1% from a US tariff refund; the free cash flow outlook includes a net refund benefit of about €200 million.
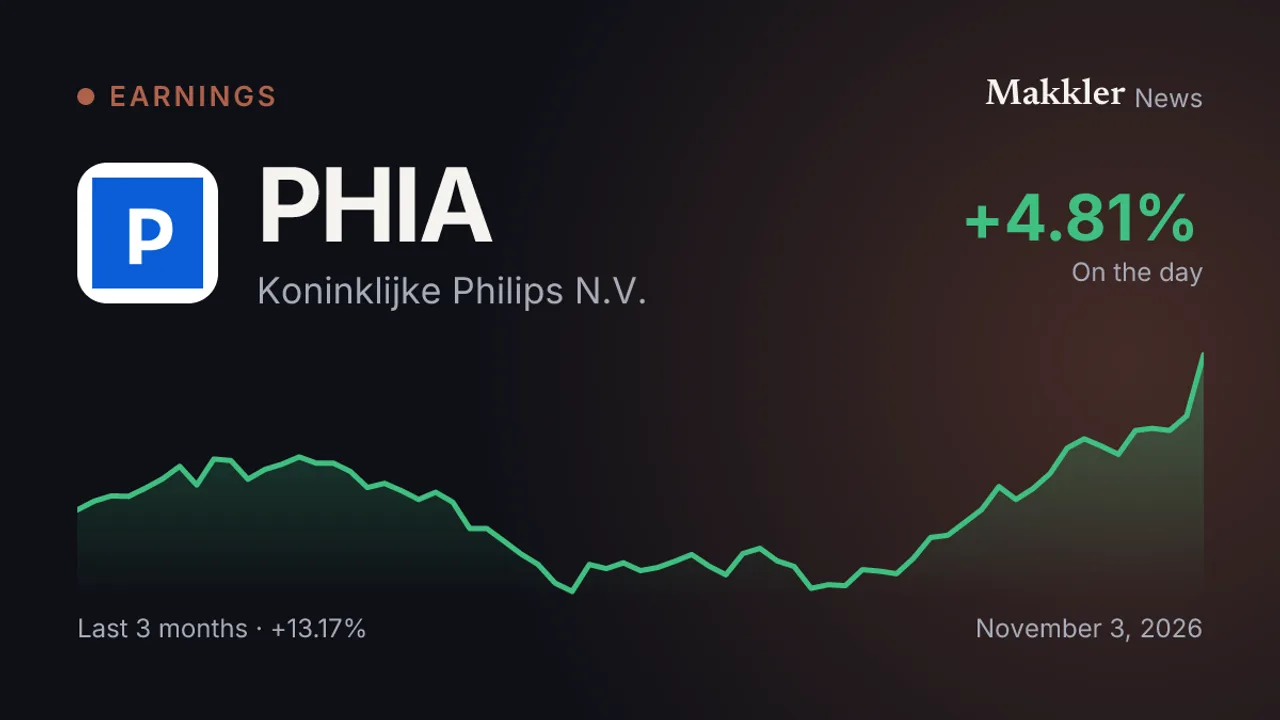
As of 8:27 UTC on Tuesday, Philips shares traded at €25.34, up 3.34% since the previous close.
This article was produced with the help of AI technology. Based on reporting by the outlets listed above.