Piper Sandler Cuts Cisco Target to $125 on Growth Concerns
The analyst kept a Neutral rating as Cisco shares fell 4.5%, despite strong recent results and a sizable AI-revenue forecast.
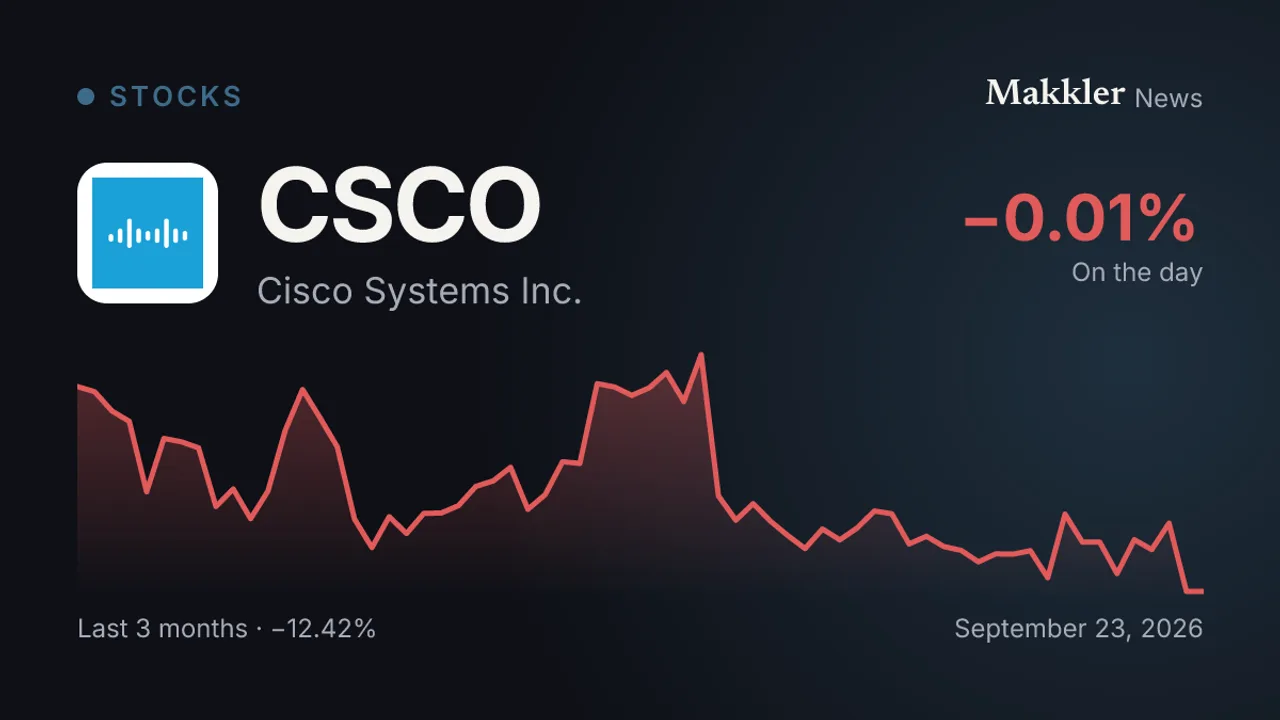
Cisco shares fell 4.5% on Tuesday, September 22, closing at $106.44 after Piper Sandler lowered its price target to $125 from $132. Analyst James Fish kept a Neutral rating, signaling caution rather than a downgrade.
The firm’s concern centers on valuation: Piper Sandler lowered its assumed price-to-earnings multiple amid fears that growth across networking equipment makers may be nearing a peak. That puts the focus on how long recent demand can keep supporting Cisco’s share price.
Cisco’s latest results were strong. Fiscal fourth-quarter revenue reached $17.3 billion, up 18% from a year earlier, while full-year fiscal 2026 revenue rose 12% to $63.3 billion.
The company forecast fiscal 2027 revenue of $72.2 billion to $73.4 billion. Compared with fiscal 2026, that range implies growth of roughly 14% to 16%, though Piper’s valuation concern suggests investors may be questioning how durable that pace will be.
AI infrastructure is a major part of the outlook. Cisco said it generated about $4 billion in revenue from hyperscalers, or large cloud providers, in fiscal 2026 and expects that figure to reach $7.5 billion in fiscal 2027.
The company also reported signs of broader demand: fourth-quarter product orders rose 35% year over year, or 25% excluding hyperscalers. Networking orders climbed 40%, marking the eighth consecutive quarter of double-digit growth in that category.
That strength leaves investors weighing two signals: robust orders and a steep AI-related revenue forecast, against concern that growth may slow after a strong run. Cisco’s shares had reached a record in June and were up about 57% over the prior year, according to Quartz.
The next test is whether demand extends beyond large cloud customers and supports Cisco’s full-year forecast. If growth holds, the current order trends offer support; if it fades, Piper’s lower valuation assumption may carry more weight.
This article was produced with the help of AI technology. Based on reporting by the outlets listed above.