Subsea 7 Raises 2026 Revenue Outlook After EBITDA Climbs 35%
The offshore contractor reported higher third-quarter revenue and profit, while lifting its full-year sales forecast to about $8 billion.
Key takeaways
- Third-quarter revenue rose 13% to $2.1 billion, and adjusted EBITDA increased 35% to $549 million.
- Subsea 7 raised its 2026 revenue outlook to about $8 billion, keeping its margin forecast near 24%.
- The company said merger approvals had been received from 13 of 16 antitrust authorities.
Subsea 7 raised its 2026 revenue outlook after third-quarter revenue grew 13% year over year to $2.1 billion. Adjusted EBITDA rose 35% to $549 million, and net income increased to $223 million from $109 million.
The company now expects full-year revenue of about $8 billion, up from its previous forecast of $7.4 billion to $7.8 billion. It kept its adjusted EBITDA margin outlook at about 24%. For 2027, Subsea 7 expects revenue of about $8 billion and a margin of about 25%.
At Sept. 30, backlog stood at $12.5 billion, including $6.1 billion expected to be carried out in 2027. Net cash, including lease liabilities, was $734 million, compared with $190 million at the end of June.
Subsea 7 said it had received 13 of 16 required antitrust approvals for its proposed merger with Saipem, with the deal now expected to close in early 2027. The Brazilian approval was conditional on selling the Seven Borealis vessel, and the company said it had begun seeking a buyer.
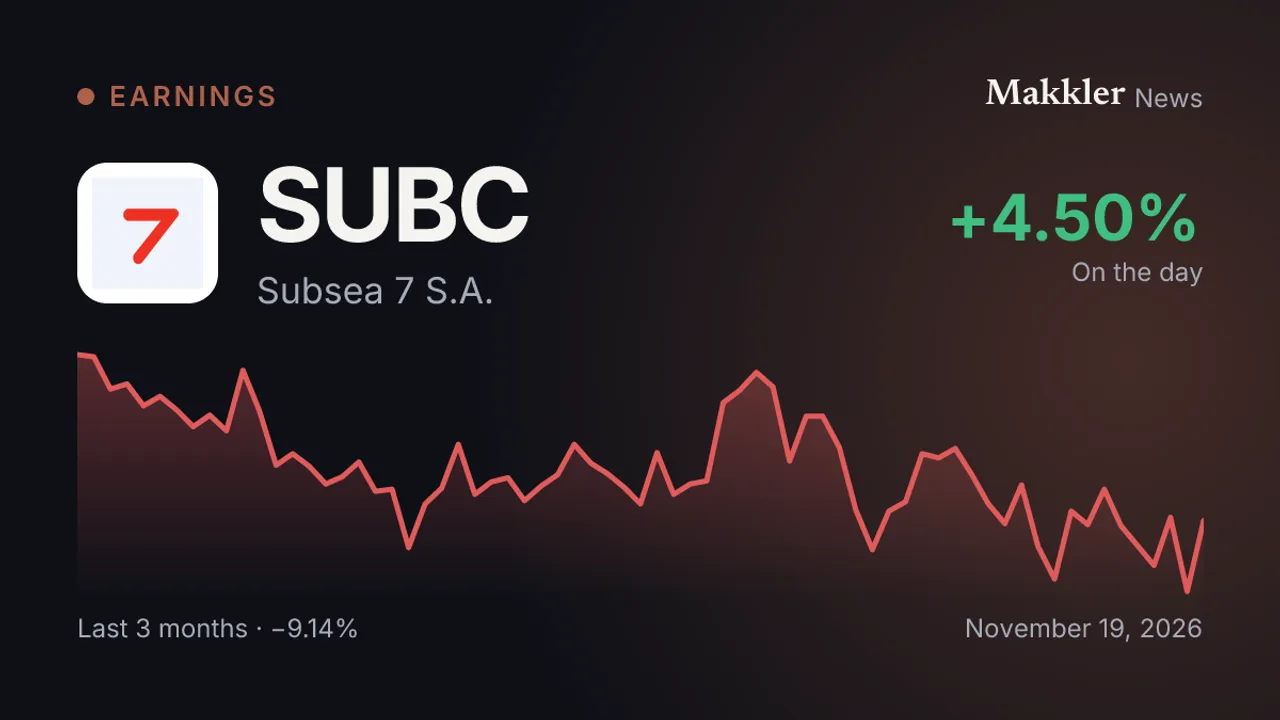
The company also agreed to sell its heavy transportation business, supporting a special dividend of €105 million outlined in the merger plan. Subsea 7 shares traded at NOK 316 as of 15:25 UTC on Nov. 19, up 4.5% since the previous close.
This article was produced with the help of AI technology. Based on reporting by the outlets listed above.