Sun Pharma Sees Specialty Drugs and Organon Deal Supporting Growth
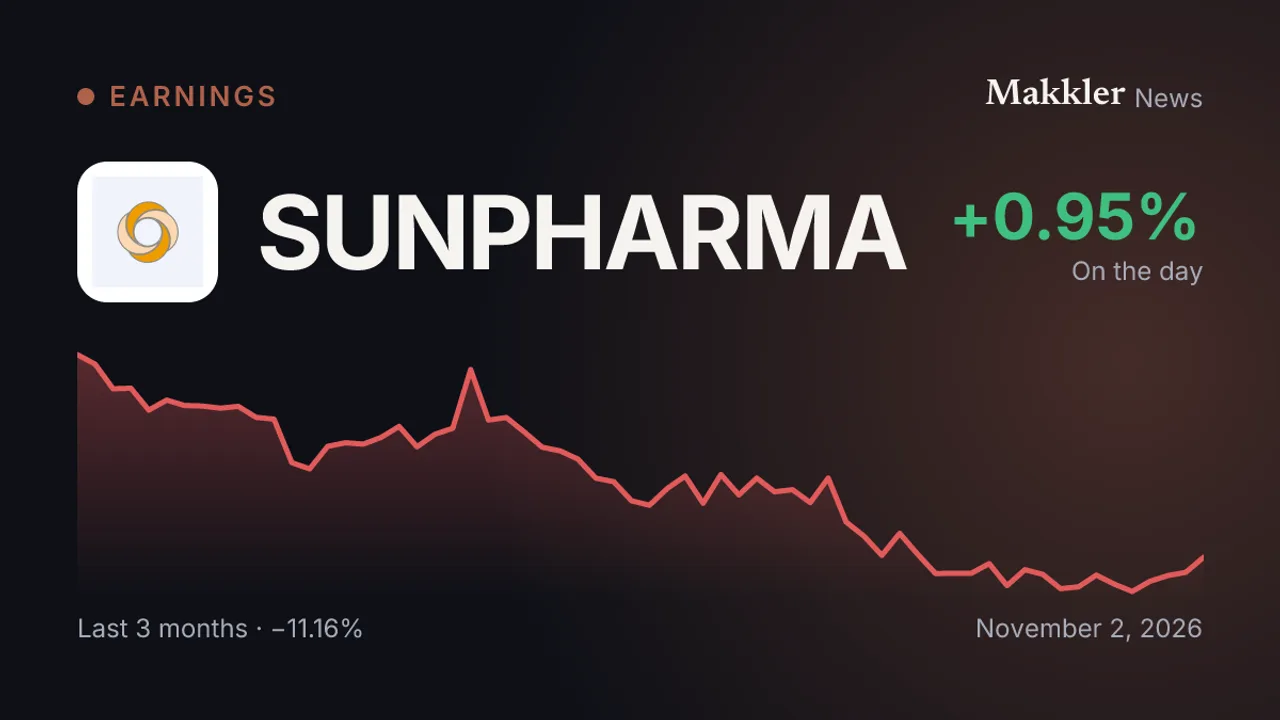
The company reported double-digit September-quarter revenue growth, while an expected Organon acquisition and specialty medicines shape its medium-term outlook.
Key takeaways
- September-quarter revenue rose at a strong double-digit rate, supported by India, emerging markets and specialty medicines.
- Sun Pharma’s India market share reached 8.6%, up from 8.3% a year earlier.
- The proposed Organon acquisition is expected to close by the fourth quarter of FY27, subject to approvals.
Sun Pharmaceutical reported strong double-digit revenue growth in the September quarter, supported by India, emerging markets and specialty medicines. One-off acquisition-related and litigation settlement costs weighed on profitability.
The company’s domestic market share reached 8.6% in the quarter, compared with 8.3% a year earlier. Its innovative medicines portfolio contributes more than one-fifth of overall sales, according to the report.
Sun expects specialty therapies including Ilumya, Unloxcyt and Leqselvi to support medium-term growth. It said Ilumya’s growth moderated partly because of execution-related factors, and expects momentum to improve after the drug’s recent US approval for psoriatic arthritis.
Late-stage pipeline assets Fibromun and Nidlegy are nearing key milestones, while diabetes candidate GL0034 remains in development. Sun expects research and development spending to rise in the second half of FY27 as development work accelerates. R&D spending was 4.8% of sales in the quarter, down from 5.4% a year earlier.
The proposed Organon acquisition is expected to be completed by the fourth quarter of FY27, subject to approvals. Choice Equity Broking retained a “BUY” rating and a ₹2,300 target, citing the specialty portfolio, pipeline and deal, but cut its FY27-28 earnings estimates by 1% to 3.6% amid weakness in the US business.
This article was produced with the help of AI technology. Based on reporting by the outlets listed above.