Patanjali Foods Profit Falls 19% as Input Costs Squeeze Margins
Quarterly revenue increased 16%, but lower profit and margins weighed on shares as brokerages assessed the outlook for demand and costs.
Key takeaways
- Patanjali Foods’ Q2 net profit fell 18.75% year on year to ₹419.76 crore.
- Revenue rose about 16% to ₹11,322.58 crore, while EBITDA fell about 23%.
- Jefferies expects a stronger second half, citing festive and wedding demand.
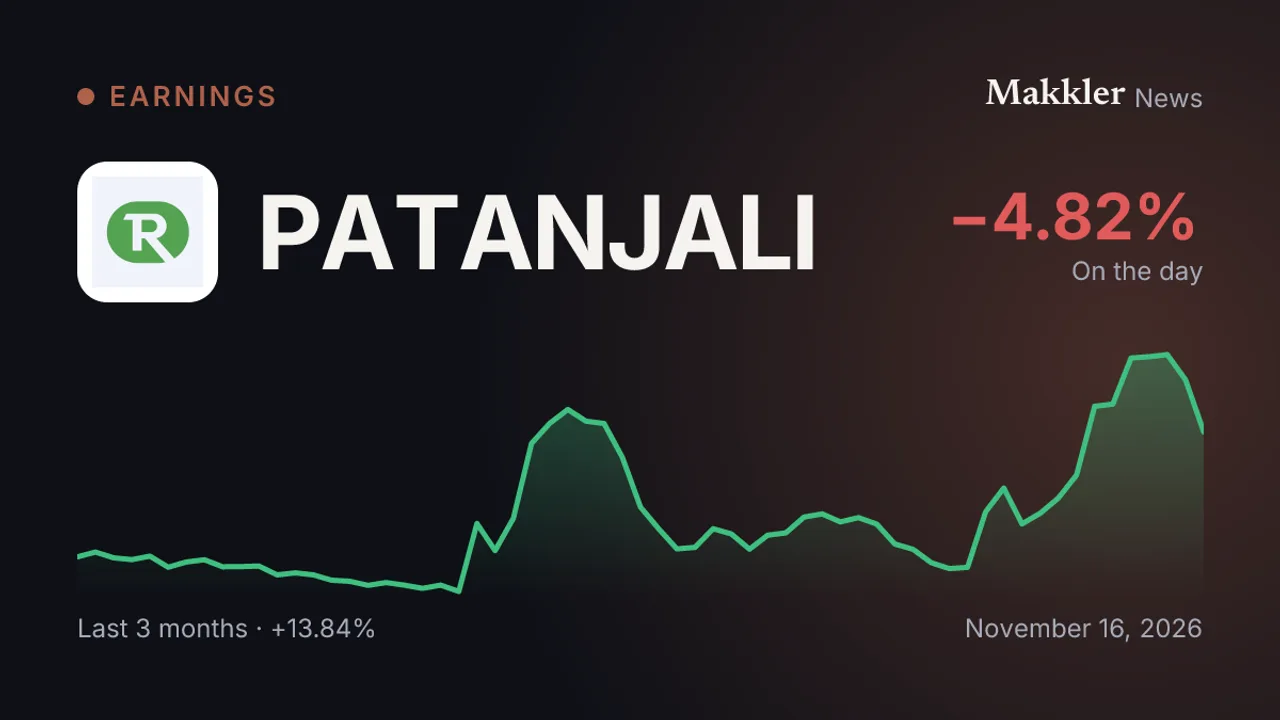
Patanjali Foods’ consolidated net profit fell 18.75% year on year to ₹419.76 crore in the second quarter of FY27, while revenue rose about 16% to ₹11,322.58 crore. As of 08:27 UTC on Monday, the shares traded at ₹401.70, down 4.58% from the previous close.
The company said growth came from higher edible-oil realizations and increased biscuit and skin-care volumes. Edible-oil sales rose about 22% to roughly ₹8,500 crore, while biscuit revenue climbed about 28% to around ₹640 crore.
Profitability weakened as input costs rose. Gross margin declined 284 basis points year on year to about 12%, and EBITDA fell about 23% to ₹430 crore, according to an ICICI Direct report. The brokerage attributed margin pressure to tight global vegetable-oil markets, weather-related palm-oil supply disruptions and biofuel-linked demand.
Jefferies said festive-season timing and edible-oil margin pressure following an import-duty cut contributed to the quarter’s shortfall. It expects a stronger second half, supported by festive and wedding demand, volume growth and improving food profitability.
Jefferies retained a Buy rating and set a ₹550 target price, while cutting its FY27 earnings estimate by 19%. ICICI Securities retained an Add rating with a ₹450 target, saying the company could navigate near-term margin pressure.
This article was produced with the help of AI technology. Based on reporting by the outlets listed above.